The Jaipur Ledger: Why India Sells Indonesia Peanuts, Not Software — and Two Tax Clocks Running Down
India–Indonesia bilateral trade reached US$11.89 billion in H1 2026 — but the composition, not the volume, is the story. Plus: GloBE registration due ~30 September, the PMK 44/2026 year-end cliff, and the data-center surge inside Indonesia’s IDR 1,010 trillion investment half.
India exports over US$200 billion of software services a year. Its leading exports to Indonesia? Buffalo meat, peanuts, cargo vehicles, tractor parts, and raw tobacco.
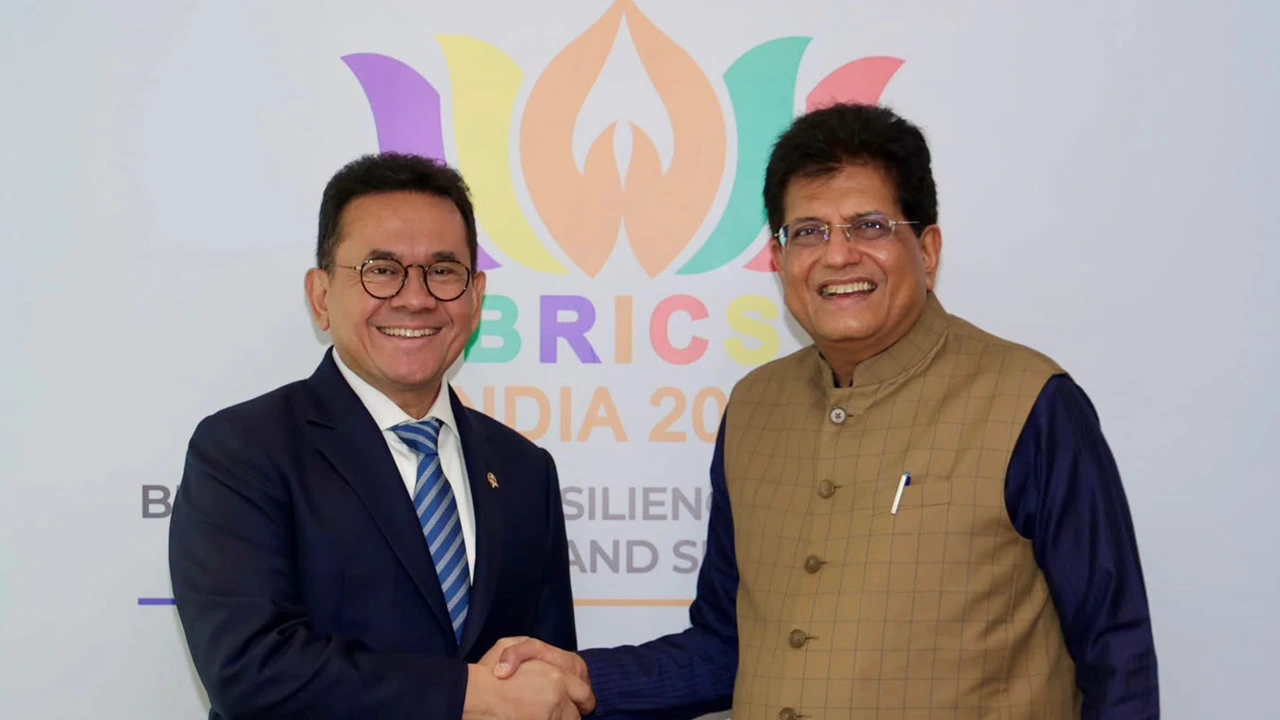
Sit with that for a moment, because it is the honest summary of the numbers two ministers put on the table this month. Last month the corridor stopped rehearsing and started signing. This month it started counting — and the count is uncomfortable. On 7 August, on the sidelines of the BRICS Trade and Industry Ministers’ Meeting in Jaipur, Trade Minister Budi Santoso and Commerce Minister Piyush Goyal confirmed H1 2026 bilateral trade of US$11.89 billion — Indonesia sending US$9.28 billion, India sending US$2.60 billion. At home, capital told a different story: IDR 1,010.6 trillion of investment realised in six months, with data centres now absorbing more capital than mining. And two compliance clocks that July flagged as future problems are now near-term ones. August 2026 is the month the corridor’s ambition met its arithmetic.
| REGISTRATION DEADLINE · GloBE TAXPAYERS · ~30 SEPTEMBER 2026 Under PER-6/PJ/2026, MNE groups above the €750 million consolidated-revenue threshold must be registered as GloBE Taxpayers by roughly 30 September 2026, with first-year top-up tax payable before the return can be submitted. Registration, notification, and the Global Information Return all run through the DGT portal. Two questions to answer this week: does the group cross the threshold on consolidated revenue, and has GIR responsibility been formally allocated between the parent and the Indonesian entity? An unallocated GIR is the most common way a compliant group misses a deadline it knew about. Separately, the PMK 44/2026 representation window still closes 31 December 2026 — ninety working days from now. |
Jaipur Puts a Number on the Handshake
The Jaipur bilateral was the first working-level test of July’s State Visit, and it produced arithmetic rather than language. Kemendag’s H1 2026 figures: total trade US$11.89 billion; Indonesian exports US$9.28 billion; Indonesian imports US$2.60 billion; surplus US$6.68 billion. Against calendar 2025 (US$23.13 billion total, US$13.46 billion surplus), the export-to-import ratio has moved from 3.78:1 to 3.57:1. The gap is narrowing — by roughly one-fifth of a point in six months.
Previous editions have described that imbalance as the thing the next decade of services trade must fix. The H1 data lets us be more precise about why it persists. Indonesia ships India coal, palm oil, stainless steel, industrial monocarboxylic fatty acids, and synthetic corundum. India ships back the list this dispatch opened with — buffalo meat, peanuts, cargo vehicles, tractor parts, raw tobacco. This is not a volume problem — it is a composition problem. The country that runs the world’s largest digital public infrastructure and supplies a fifth of the planet’s generic medicine by volume is selling Indonesia commodities. And composition problems are not solved by tariff schedules.
Three commitments came out of Jaipur, and the sequencing matters more than the headlines. On AITIGA, Indonesia’s liberalisation rate currently sits at 41.9% against a committed 80% market-access target; phased offers tabled by July covered roughly 57% of that target, with substantial conclusion aimed at October 2026. On the ID-IN PTA, India responded positively — but technical discussions are sequenced to begin after AITIGA concludes, which realistically means Q4 2026 at the earliest. On WGTI, Indonesia backed India hosting the second Working Group meeting within 2026, executing a July Joint Statement mandate. For exporters, the actionable window is the AITIGA tariff schedule between now and October — not the PTA, which is next year’s negotiation.
One housekeeping note that has cost more than one board meeting: Indian and Indonesian trade statistics do not agree, and the gap is base, not error. IBEF reports US$28.15 billion for FY2024–25 (April–March), against a US$38.84 billion peak in FY2022–23 driven by the coal and palm-oil price spike. Kemendag reports US$23.13 billion for CY2025. Same corridor, different clocks. Fix which dataset your board paper uses before your counterparty picks the other one.
The Compliance Desk: Two Clocks and a Scheme Nobody Elects
July’s dispatch mapped the instruments. August is about dates. Two of them are close enough to plan around, and a third item — largely unremarked in this series — is quietly costing senior Indian executives money every year they stay.
The Territorial Scheme for Foreign Nationals — and Why Most People Miss It
Under PMK 18/2021, a foreign national who becomes an Indonesian resident tax subject can be taxed on Indonesian-sourced income only, for four years. It is widely described in expat circles as “0% tax on foreign income,” which is close enough to true and wrong in three ways that matter.
First, it is not automatic. It must be applied for on the Appendix III template, with the DGT issuing an approval or rejection within ten days. No approval letter, no scheme. Second, the four-year clock runs from the date of first residency and does not pause — leave Indonesia for eighteen months and return, and you resume where you left off, not where you started. Third, it is an either/or election against tax treaty benefits under the India–Indonesia DTAA. For an executive with material Indian-sourced income — rental, dividend, capital gains — the treaty route can be worth more than the exemption. Eligibility itself is narrow: a listed position under Appendix II, a science/technology/mathematics background, a knowledge-transfer obligation to local staff, and evidence by certificate, diploma, or five years’ experience. Run both scenarios before electing; the election is not easily unwound.
| Instrument | The Date That Matters | What It Means for Indo-Indian Entities |
| PER-6/PJ/2026 GloBE / Pillar Two | ~30 September 2026 — GloBE Taxpayer registration. Top-up tax payable before the return can be filed. UTPR fully operational for the 2026 tax year. | Confirm the €750m consolidated-revenue test at group level, then allocate GIR responsibility in writing between parent and PT. Stand up per-jurisdiction ETR tracking now — a 15% Indonesian ETR proved after year-end close is proof arriving too late to change anything. |
| PMK 44/2026 Tax representation | 31 December 2026 — close of the transition window for brevet / tax-education holders acting as kuasa. | Ninety working days remain. The SKT application route is still not open, so the reliable path is moving the mandate to a licensed consultant. An expatriate finance director who personally signs filings falls into “other parties” and needs an SKT — currently unobtainable. |
| PMK 18/2021 Territorial scheme | Four years from first residency — no pause, no restart. DGT decision within 10 days of a complete application. | Audit your expatriate bench: who is in year three, who never applied, and who would be better off under the DTAA. This is an annual, quantifiable saving that most Indian-owned PTs have never modelled. |
The three dated obligations shaping the August–December 2026 compliance desk.
Trade Pulse: Where the Capital Actually Went
Investment realisation crossed a symbolic line in H1 2026: IDR 1,010.6 trillion, up 7.2% year on year, absorbing 1,448,862 workers — about 15% more than the same period last year. Two structural signals sit under the headline and neither has appeared in this dispatch before.
First, foreign and domestic capital have converged: PMA at IDR 507.6 trillion (50.2%) against PMDN at IDR 502.9 trillion (49.8%), the tightest split in years. Geography rebalanced in parallel — outside Java IDR 507.8 trillion against Java IDR 502.8 trillion, with DKI Jakarta still the largest single province at IDR 173.6 trillion.
Second, and more consequential for our community: “other services” — predominantly data centres — took IDR 114 trillion in six months. That is second only to basic metals and metal goods at IDR 150.4 trillion, and ahead of mining (IDR 105 trillion) and transport/warehousing/telecommunications (IDR 102.7 trillion). Indonesia is now capitalising compute at close to the rate it capitalises smelters. For Indian IT services, cloud engineering, and managed-security firms, that single line is the most relevant number BKPM has published this year — and unlike a trade agreement, the capital is already committed and the buildings are going up.
| “Indonesia is now capitalising compute at close to the rate it capitalises smelters. For Indian IT, cloud, and security firms, that is the most relevant number BKPM has published this year.” |
The Tech Handshake: Architecture, Not Vendor
This column has argued for four editions that the corridor’s opportunity is capacity, not licences. The H1 numbers let us stop arguing the principle and name the specific openings. Each of the four fronts below has moved materially since July — and in three of them the constraint has shifted from whether to who gets there first.
The Knowledge Bridge
The skills conversation needs updating. IDR 114 trillion of data-centre capex does not primarily demand more bootcamp graduates — it demands people who can operate the estate: site reliability, workload migration, capacity and power planning, thermal management, and the compliance tooling that sits over regulated workloads. That is a narrower and scarcer skill set than “cloud and AI,” and Indonesia does not have it in domestic supply at the scale being built. The Tagore–Dewantara Year (2026–27) designated at the State Visit is the institutional vehicle worth using here — not for cultural programming, but as cover for co-badged, mutually recognised certification between Indian training institutions and Indonesian polytechnics. Recognition, not volume, is the bottleneck: an Indonesian engineer holding an Indian certification that no Indonesian employer formally recognises has been trained, not employed.
The Digital Bodyguard
Coretax exclusivity, confirmed in July, changed the security question and almost nobody has repriced it. When supervision, collection, objections, and appeals all live in one platform and there is no paper fallback, a compromised Coretax credential stops being an IT incident and becomes a total-loss event: an attacker with a valid PIC certificate can file, respond, concede, or withdraw on your behalf, and the platform will treat it as you. PMK 44/2026 sharpens this further by formalising exactly who may act as kuasa — which means the representation chain is now a documented, auditable identity graph rather than an informal habit. The control that matters in Q4 is unglamorous: privileged-access management over every e-certificate, a named owner per credential, mandatory MFA, quarterly re-attestation, and a documented revocation path for departing staff and terminated consultants. Firms that have already built this for themselves have a product; most Indonesian mid-market companies face the identical exposure with less capacity to close it.
The UMKM Engine
The Indonesia Open Network (ION) launched on 13 July 2026, welcomed by President Prabowo and PM Modi during the State Visit. It is built on India’s ONDC architecture — adapted rather than transplanted — and convened by the Ministry of MSMEs and KomDigi with APINDO, SMESCO, Google.org (US$1.5 million in grants), Networks for Humanity, and founding partners including Indosat Ooredoo Hutchison and Protean eGov Technologies. The promise is interoperability without platform lock-in: join once, sell everywhere.
Here is the part worth paying for. ONDC’s hard lesson in India was never the protocol — it was seller onboarding and catalogue quality. Open networks fail quietly when the catalogue is thin, the product data is inconsistent, and small sellers churn out within a quarter. Indian firms that lived through that specific failure are worth more to an ION participant than any firm arriving with a platform to sell. And a caution: commission-reduction figures for ION are circulating without an ION source behind them. Do not put an unsourced fee benchmark in a client deck — the network has not published one.
The Payment Highway
For five editions this column has tracked QRIS–UPI as “short of live.” It remains short of live — the leaders’ commitment is end-2026, the technical work is described as advanced, and there is no published go-live date, no pilot settlement window, and no merchant onboarding. But there is a more useful point to make than another countdown: QRIS–UPI is a retail rail, and it is not going to settle your invoices. It is built for a person scanning a code — a traveller, a shopper, a small merchant. Treasury teams waiting for it to solve intercompany or B2B settlement are waiting for the wrong thing.
The instrument that does address B2B already exists and was noted here last month: the rupee–rupiah Local Currency Settlement framework, with an RBI-published INR/IDR reference rate. It is available now, it is bankable now, and it does not require a central-bank launch event. Ask your bank what INR/IDR reference-rate pricing it will quote on your recurring flows, and put group netting and forward cover in place this quarter. Waiting for infrastructure is not a treasury strategy.
| COMMUNITY CHALLENGE · AUGUST 2026 Jaipur gave us the ledger. The uncomfortable question is what sits in your own column. Before your next board paper, run this three-question test on your Indonesian operation. |
- Split my Indonesian revenue two ways — commodity versus capability, goods versus services. What share would survive if the tariff line changed tomorrow, and what share is genuinely tied to something I built here?
- Have I named an owner for every Coretax e-certificate and every kuasa in the chain, with MFA and a revocation path — or would a departing finance manager still be able to file for me in January?
- Of the IDR 114 trillion going into Indonesian data centres this half, am I in a single procurement conversation — or reading about it?
Reply to this dispatch with the answer that surprised you most — those that resonate will be featured (anonymously) in September.
Sampai jumpa di bulan depan. (See you next month.)
Quick Compliance Checklist · September 2026 Lookahead
Ten action items to clear before end-September 2026:
| Tax & Coretax | Corporate & Treasury |
| ▢ Complete GloBE Taxpayer registration and confirm top-up tax is funded — payment precedes filing (PER-6/PJ/2026). | ▢ Model your tariff lines against the AITIGA 80% liberalisation target before the October substantial-conclusion window. |
| ▢ Allocate Global Information Return responsibility in writing between parent and Indonesian entity. | ▢ Do not build the 2027 plan on a live QRIS–UPI link — and do not expect it to settle B2B when it lands. |
| ▢ Move every kuasa mandate to a licensed consultant now; do not wait on the unpublished SKT route (PMK 44/2026). | ▢ Ask your bank for INR/IDR reference-rate pricing; put group netting and forward cover on recurring flows. |
| ▢ Run a privileged-access review over all Coretax e-certificates — named owner, MFA, quarterly re-attestation, revocation path. | ▢ If you sell IT, cloud, security, or managed services — open procurement conversations with Indonesian data-centre operators. |
| ▢ Audit the expatriate bench against PMK 18/2021: who is in year three, who never applied, who is better off under the DTAA. | ▢ Fix which trade dataset the board paper uses: Indian FY or Indonesian CY. They differ by billions. |
| ABOUT THE AUTHOR
CA Loganathan Anandan, FCA, CISA, CDPSE, CFE Loganathan is President Director of PT JCSS Management Consulting, with two decades of advisory experience across the India–Indonesia–Singapore corridor. His practice spans cybersecurity, AI strategy, cross-border tax, regulatory compliance, and corporate integration — with a focus on bringing Indian frugal-innovation discipline into Indonesia’s mid-market. |

Follow us on Instagram @indoindians